

Dodge Durango Lease Guide for Long Island Buyers
A Long Island family can need three things from one SUV, school-run practicality, room for weekend luggage, and enough muscle for a trailer, while still watching every recurring household expense. That’s why a Dodge Durango lease gets attention. It offers access to a new three-row SUV without committing the family to ownership for the long term, but the advertised monthly payment rarely tells the whole story.
The payment changes with trim, engine, mileage allowance, residual value, money factor, taxes, and cash due at signing. A shopper comparing a Durango with a Jeep Grand Cherokee lease, Jeep Wrangler lease, or RAM 1500 Big Horn or Lone Star lease should compare the complete lease structure, not just the number printed in a search result.
Table of Contents
- Why Long Island Families Choose a Dodge Durango Lease
- How Leasing a Durango Compares to Buying
- Trim Levels and Powertrain Choices That Shape Your Payment
- Step by Step Process to Lease at Security Dodge
- Negotiation Tactics and Money Saving Lease Strategies
- Real Payment Scenarios and Local Incentives Near Amityville
Why Long Island Families Choose a Dodge Durango Lease
A family leaving Nassau County for a school pickup in the morning, a Saturday drive toward the Hamptons, and a Sunday visit to relatives needs more than a low payment. They need seating flexibility, cargo space, winter confidence, and towing capability that won’t feel marginal when plans change. The Durango fits that profile because it combines SUV utility with available V6 and V8 powertrains.
Leasing can make sense for families who want a new vehicle on a predictable replacement cycle. A lease commonly lets the driver use the SUV for a defined term, then return it or pursue the available end-of-lease options. That structure can suit parents who want current driver-assistance and connectivity features without planning to keep the same vehicle for many years.
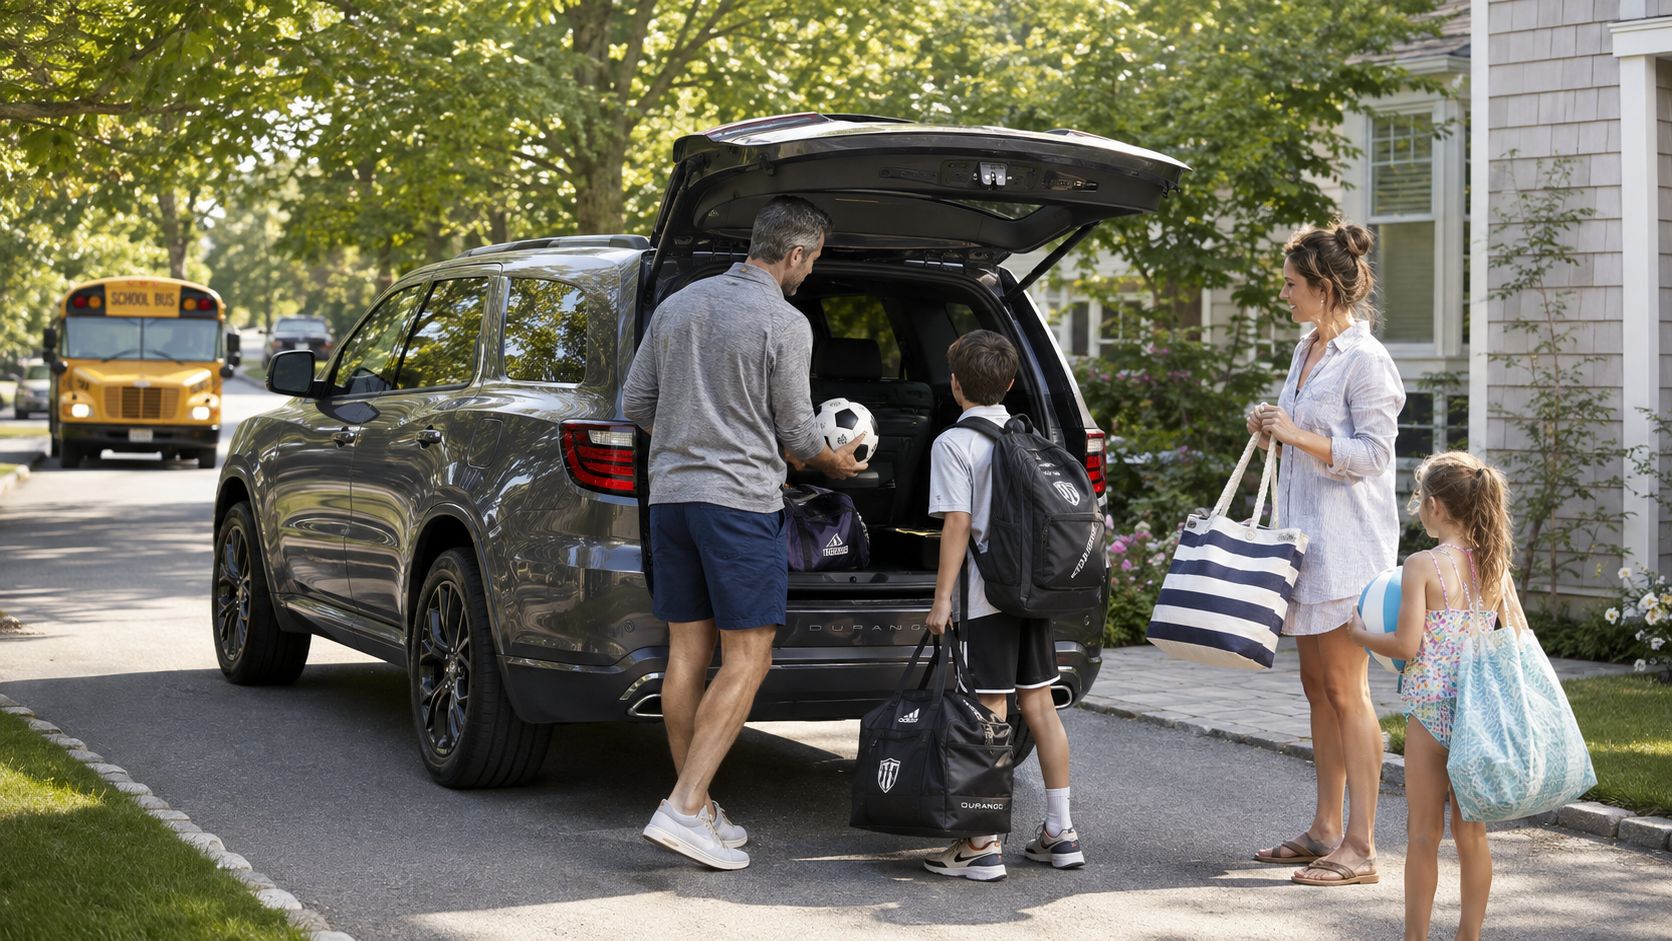
Why the local environment matters
Long Island driving brings its own ownership concerns. Winter road salt, stop-and-go traffic, crowded parking areas, and frequent short trips can make a newer vehicle appealing. Leasing doesn’t eliminate operating costs or responsibility for proper care, but it can reduce the concern about what the SUV will be worth years later when the family is ready to move on.
Cash flow also matters locally. A household may prefer to keep money available for property taxes, tuition, insurance, commuting, and activities instead of tying a large amount to a vehicle. That doesn’t automatically make leasing cheaper. It means the family should judge the lease by its full cash requirement and effective monthly cost.
Amityville sits in Suffolk County, with nearby communities including Copiague, East Massapequa, North Amityville, Massapequa Park, and Lindenhurst, as listed by Suffolk County’s towns and villages information. For shoppers around these areas, the right dealership conversation should begin with the vehicle’s actual use, not a generic lease advertisement.
Practical rule: Lease the Durango because its size, capability, and replacement flexibility fit your household. Don’t lease it simply because the headline payment looks comfortable.
The Durango belongs in a broader comparison. A Grand Cherokee may suit a family that doesn’t need three-row space. A Wrangler fits buyers who prioritize open-air capability and distinctive design. A RAM 1500 Big Horn or Lone Star makes more sense when bed utility and truck capability outrank SUV maneuverability. The Durango is the middle path for families that want passenger space and available towing strength in one vehicle.
How Leasing a Durango Compares to Buying
Choosing between a Durango lease and purchase starts with one question: do you want temporary use or long-term ownership? Buying pays for ownership, while leasing pays for the vehicle’s expected depreciation during the contract, plus finance charges, taxes, and applicable fees. A purchase can build equity. A lease leaves the vehicle’s future value with the leasing company, subject to the contract.
The lease worksheet contains three figures that determine the hidden math:
- Capitalized cost: The negotiated amount used to calculate the lease, adjusted for eligible fees, trade equity, and incentives.
- Residual value: The projected value at lease end, usually shown as a percentage of MSRP. Federal Reserve leasing guidance explains that the lease term and permitted mileage are set at the start and used to determine the residual.
- Money factor: The lease’s finance rate. To compare it with an approximate APR, multiply the money factor by 2,400. The calculation is also explained in this lease-payment explanation.
The monthly payment combines depreciation and finance charges. Depreciation comes from the difference between adjusted capitalized cost and residual value. The finance portion uses the average of those two amounts. A lower negotiated price reduces depreciation. A lower money factor reduces finance cost. Due-at-signing cash can make the advertised payment look lower without reducing the lease’s actual cost, so compare the total cash required and all scheduled payments.
A clear comparison
| Cost Factor | 36-Month Lease | 72-Month Purchase |
|---|---|---|
| What you pay for | Use of the Durango during the contract | The vehicle and eventual ownership |
| Equity | Usually none unless you buy at lease end | Builds as the loan balance falls |
| Mileage | Contract allowance applies | No lease mileage limit |
| End of term | Return, replace, or explore purchase options | Continue owning after the loan ends |
| Main risks | Excess mileage, damage, unpaid charges, and contract fees | Depreciation, repair costs after warranty coverage, and long-term value |
| Best fit | Drivers who want a newer SUV and a planned replacement cycle | Drivers who expect to keep the Durango for a long time |
A familiar 36-month and 10,000-mile-per-year lease can fit a moderate driver. Long Island commuting can expose an inaccurate estimate quickly. Regular use of the Long Island Expressway, Northern State Parkway, Southern State Parkway, or cross-island routes may push annual mileage beyond the contract allowance. Check odometer history, commuting distance, school runs, and weekend travel before signing. The written allowance controls the cost.
New leases commonly use residual values based on a 15,000-mile annual basis. A contract above that allowance can reduce the residual by $0.15 per excess mile. The CULA lease program policies give a three-year lease at 18,000 miles per year as an example producing a $1,350 residual reduction. Ask for the mileage adjustment in writing before accepting a higher allowance.
Buying generally suits high-mileage drivers and families that plan to keep the SUV well beyond the financing period. Leasing suits drivers who want a newer vehicle, a scheduled replacement, and less exposure to resale uncertainty. Neither choice should be judged by the monthly payment alone.
Request the total due at signing, total scheduled payments, mileage allowance, purchase option, disposition terms, and wear standards in writing. Then compare the effective monthly cost, including upfront cash, against the purchase’s loan payments, ownership period, equity, and repair exposure.
Trim Levels and Powertrain Choices That Shape Your Payment
The Durango’s trim and engine choice can change the lease more than shoppers expect. A higher trim may deliver better equipment and a stronger residual percentage, but its larger MSRP can still create a larger depreciation amount and a higher payment. The right choice isn’t the most expensive trim with the highest residual. It’s the configuration that supplies what the family will use.
The fuel-economy difference is material. The Dodge Durango specifications presented by Car and Driver identify EPA-rated fuel economy of 18 mpg city and 25 mpg highway for the V6, compared with 14 mpg city and 22 mpg highway for the V8. That gap affects the budget throughout the lease, especially for a commuter who drives daily or a family that regularly tows.
Choosing between the V6 and V8
The V6 is the rational choice for daily family transportation when towing and acceleration demands remain moderate. Its lower fuel consumption usually supports a more manageable operating budget, even if the lease payment itself doesn’t show that difference.
The V8 earns consideration when performance or towing is a genuine requirement. The Dodge Canada Durango capability information lists maximum towing capacity ranging from 6,200 pounds on the V6 to 8,700 pounds on properly equipped V8 configurations, including Tow N Go variants. That added capability comes with more expensive hardware and calibration, and the configuration can include larger engines, AWD, and tow equipment.
Match the tow rating to the trailer you actually own or plan to use. Extra capacity can be useful, but unused capability still raises the vehicle cost.
Residual value is not the whole answer
Independent listings show a 2026 Durango GT AWD at about 53% residual on a 42-month, 10,000-mile structure, while a 2026 Durango SRT Hellcat AWD listing has a different residual profile and a far higher payment. Those figures appear in the Edmunds Durango lease-deals discussion, and they demonstrate why one generic Durango payment can mislead.
A mid-range configuration can deliver a more sensible balance than a performance flagship. The SXT may keep acquisition cost under control. GT and R/T shoppers should compare equipment against payment carefully. Citadel buyers need to confirm that added luxury justifies the higher capitalized cost. Trailer Tow Group equipment and premium audio can increase the amount being financed through the lease, so add options only when they solve a real need.
Step by Step Process to Lease at Security Dodge
A clean Durango lease starts with the numbers you bring to the dealership. Set your annual mileage, decide whether AWD and towing equipment are necessary, and choose the cash amount you can safely pay at signing. Keep that cash figure separate from the advertised monthly payment. A large upfront payment can make an offer look cheaper while raising your total risk if the vehicle is stolen or totaled.
Bring a valid New York driver’s license, proof of insurance, and recent pay stubs. If you have a trade-in, bring the title or loan information and an accurate payoff statement.
Prepare the application
A credit application usually creates a hard inquiry. Submit one after you are ready to evaluate a real offer, not while casually checking several stores. The lender reviews income, debt, credit history, and the selected Durango before setting approval terms. A credit tier does not guarantee a specific money factor or monthly payment.
Inspect the actual SUV before discussing final terms. Check seating, cargo access, visibility, tires, installed equipment, and the window sticker. If your family is comparing a Durango with a Grand Cherokee, Wrangler, or RAM 1500 Big Horn or Lone Star, drive each model with its usual passengers and cargo.
Read the worksheet line by line
Ask the finance manager to show:
- MSRP and selling price.
- Every rebate or incentive.
- Adjusted capitalized cost.
- Residual value and mileage allowance.
- Money factor.
- Lease term and monthly payment.
- Taxes, registration, acquisition charges, disposition terms, and total cash due at signing.
Your dealership worksheet should reflect all applicable fees and incentives, which you can review before committing. Add every upfront charge to the scheduled payments before comparing offers. That calculation exposes the true monthly cost and prevents due-at-signing cash from distorting the deal.
Review add-on products carefully. GAP coverage may already be included in the lender’s lease structure, so ask whether separate coverage duplicates it. Paint protection and extended warranties can provide limited value on a short lease, especially when the contract already requires maintenance and sets return-condition standards. Decline any product you cannot explain in plain language.
Before signing, inspect the Durango again. Confirm the VIN, mileage, and installed equipment, then ask when the first payment is due. Keep copies of the signed contract, insurance documents, inspection records, and receipts.
Negotiation Tactics and Money Saving Lease Strategies
Start with the selling price, not the monthly payment. A low advertised payment can hide substantial due-at-signing cash, a longer term, reduced mileage, or dealer-installed products. Ask for a written worksheet listing MSRP, selling price, incentives, adjusted capitalized cost, residual value, money factor, fees, and total upfront cash. Request a complete worksheet from your dealer showing every line item before signing.
Compare written offers from dealers across the Tri-State area only when the vehicles and contract terms match. A V6 GT with one mileage allowance cannot be compared fairly with a V8 R/T using another. Trim, powertrain, equipment, and mileage all change the payment. Your goal is a lower adjusted capitalized cost without giving up the capability your family needs.
Audit the finance rate
The money factor deserves direct attention. Multiply it by 2,400 for an approximate APR equivalent, using the lease-payment method explained earlier. If the lender’s buy rate is available to the dealer but the worksheet shows a higher factor, ask for the reason. Even a modest markup affects every payment during the contract.
Multiple security deposits may reduce the money factor on approved Chrysler Capital leases, depending on the program and your eligibility. Ask for the exact reduction, total deposit, and refund rules. Do the math before committing. Cash held in deposits has an opportunity cost, and the contract terms determine when and how it returns.
Cash-control rule: Keep due-at-signing cash as low as practical. A large upfront payment can be difficult to recover if the vehicle is stolen or declared a total loss early in the lease.
Advertised payments can look reasonable while the effective cost rises sharply after upfront cash is included. Current third-party listings show 2026 Durango offers around $506 to $507 per month with about $4,499 due at signing, while other listings show roughly $5,000 or more due upfront. Use the Dodge incentive page to verify current manufacturer offers, then use the dealer worksheet to confirm local taxes and fees.
Timing can improve your negotiating position, especially near month-end, quarter-end, or a model-year changeover when inventory and volume targets matter. Ask about loyalty, conquest, military, and first-responder programs. Get eligibility rules and stacking restrictions in writing. An incentive reduces the lease cost only when you qualify and the credit appears in the worksheet.
Real Payment Scenarios and Local Incentives Near Amityville
A responsible Durango comparison needs complete figures, not invented examples presented as quotes. Current verified listings support a payment range around $506 to $507 per month with approximately $4,499 due at signing for certain 2026 offers, but they don’t provide enough verified information to create accurate MSRP, negotiated cap cost, money factor, residual, term, mileage, and payment combinations for SXT, R/T, and Citadel scenarios.
The table below shows what should be requested before accepting an offer. “Not provided” is more useful than a fabricated number because every missing field can change the effective payment.
| Trim Level | MSRP | Negotiated Cap Cost | Residual % | Money Factor | Term / Miles | Est. Monthly Payment |
|---|---|---|---|---|---|---|
| SXT | Confirm on worksheet | Confirm on worksheet | Confirm on worksheet | Confirm on worksheet | Confirm term and mileage | Quote required |
| R/T | Confirm on worksheet | Confirm on worksheet | Confirm on worksheet | Confirm on worksheet | Confirm term and mileage | Quote required |
| Citadel | Confirm on worksheet | Confirm on worksheet | Confirm on worksheet | Confirm on worksheet | Confirm term and mileage | Quote required |
The numbers that deserve verification
Use the current offer as a negotiation reference, not as a promise. Confirm whether the payment includes taxes, acquisition charges, registration, dealer fees, and any add-ons. Then calculate the effective monthly cost by spreading all due-at-signing cash across the lease term and adding it to the advertised payment.
The residual also deserves trim-level review. A listed 2026 Durango GT AWD residual of about 53% on a 42-month, 10,000-mile structure cannot be transferred automatically to an SXT, R/T, Citadel, or SRT Hellcat. The Edmunds lease-deals discussion shows different residual treatment and a much higher payment for the SRT Hellcat AWD, reinforcing the need to evaluate the exact VIN and contract.
For a Long Island buyer near Amityville, Copiague, East Massapequa, North Amityville, Massapequa Park, or Lindenhurst, confirm the local tax calculation and registration charges before comparing offers. Ask whether loyalty or conquest incentives apply to your current vehicle, and verify any military or first-responder program directly on the written offer. Don’t rely on a verbal promise that an incentive will “be added later.”
Before signing, check this list:
- Vehicle: Exact trim, engine, drivetrain, options, and VIN.
- Lease structure: Term, annual mileage, residual, and money factor.
- Cash: Total due at signing, including taxes and fees.
- Protection: GAP treatment, wear standards, maintenance duties, and disposition terms.
- Exit: Return process, purchase option, and excess-mile charge.
Security Dodge Chrysler Jeep RAM offers new Dodge vehicles and lease or purchase assistance for shoppers comparing the Durango with the Grand Cherokee, Wrangler, or RAM 1500. Visit Security Dodge Chrysler Jeep RAM with your mileage, towing needs, and target cash due at signing ready, and request a complete Durango lease worksheet before you commit.
0 comment(s) so far on Dodge Durango Lease Guide for Long Island Buyers